Utah
Storm, hail, and insurance claims
Utah gets hail. It is not a Gulf Coast story that somehow does not apply here. Spring and summer thunderstorms bruise architectural shingles along the Wasatch Front, dent metal, and crack tile. Monsoon cells do the same in Washington County. The useful response is a documented roof and a clear conversation with your insurer — not a door-knock script.
Emergency
24/7 emergency tarping
The phone is answered 24/7. If weather has opened a roof, call (385) 333-9637. A plastic cover or a blue tarp, held with sandbags, is a temporary dry-in. It is not a finished repair and it is not an approved insurance claim. We do not promise an arrival time. Inspections are still booked during office hours, 9:00 AM–5:00 PM, 7 days a week.
Emergency covers and hail marks
Plastic and blue tarps weighted with sandbags, and hail hits circled in chalk. A cover keeps weather out. It is not a finished repair and it is not an approved claim.
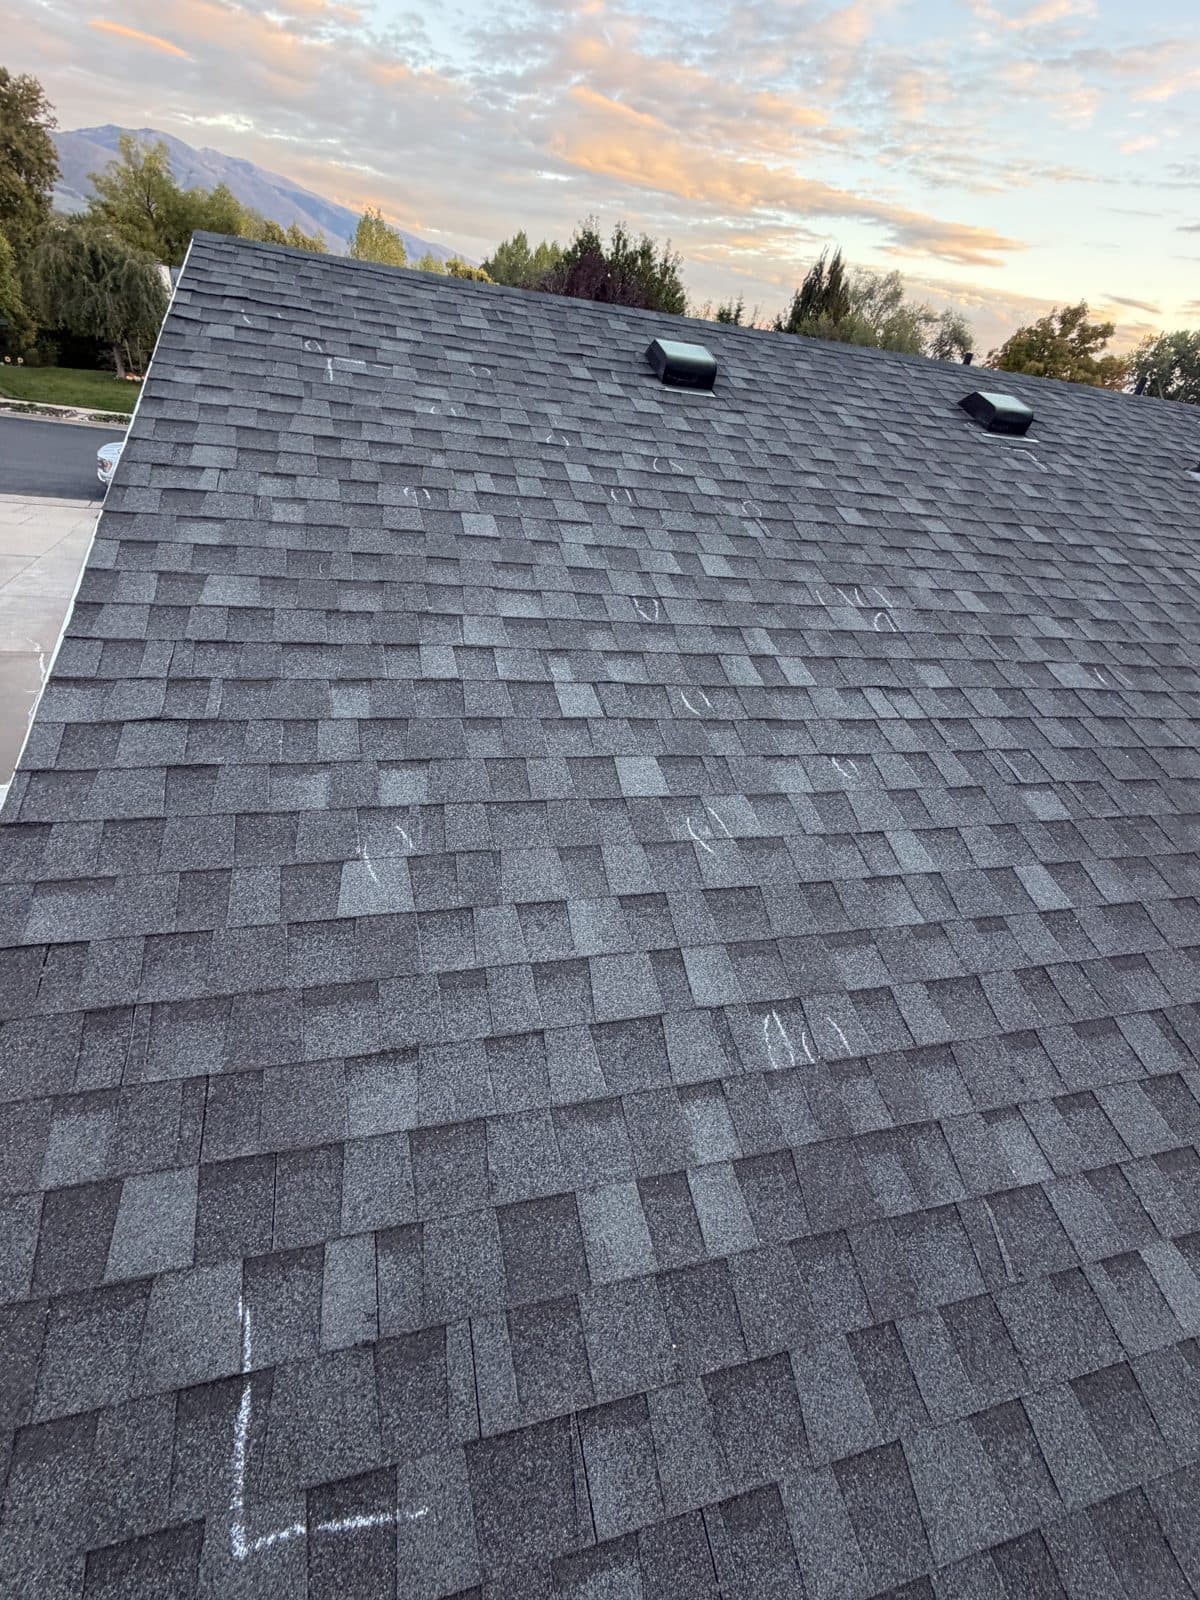
Hail hits circled during an inspection 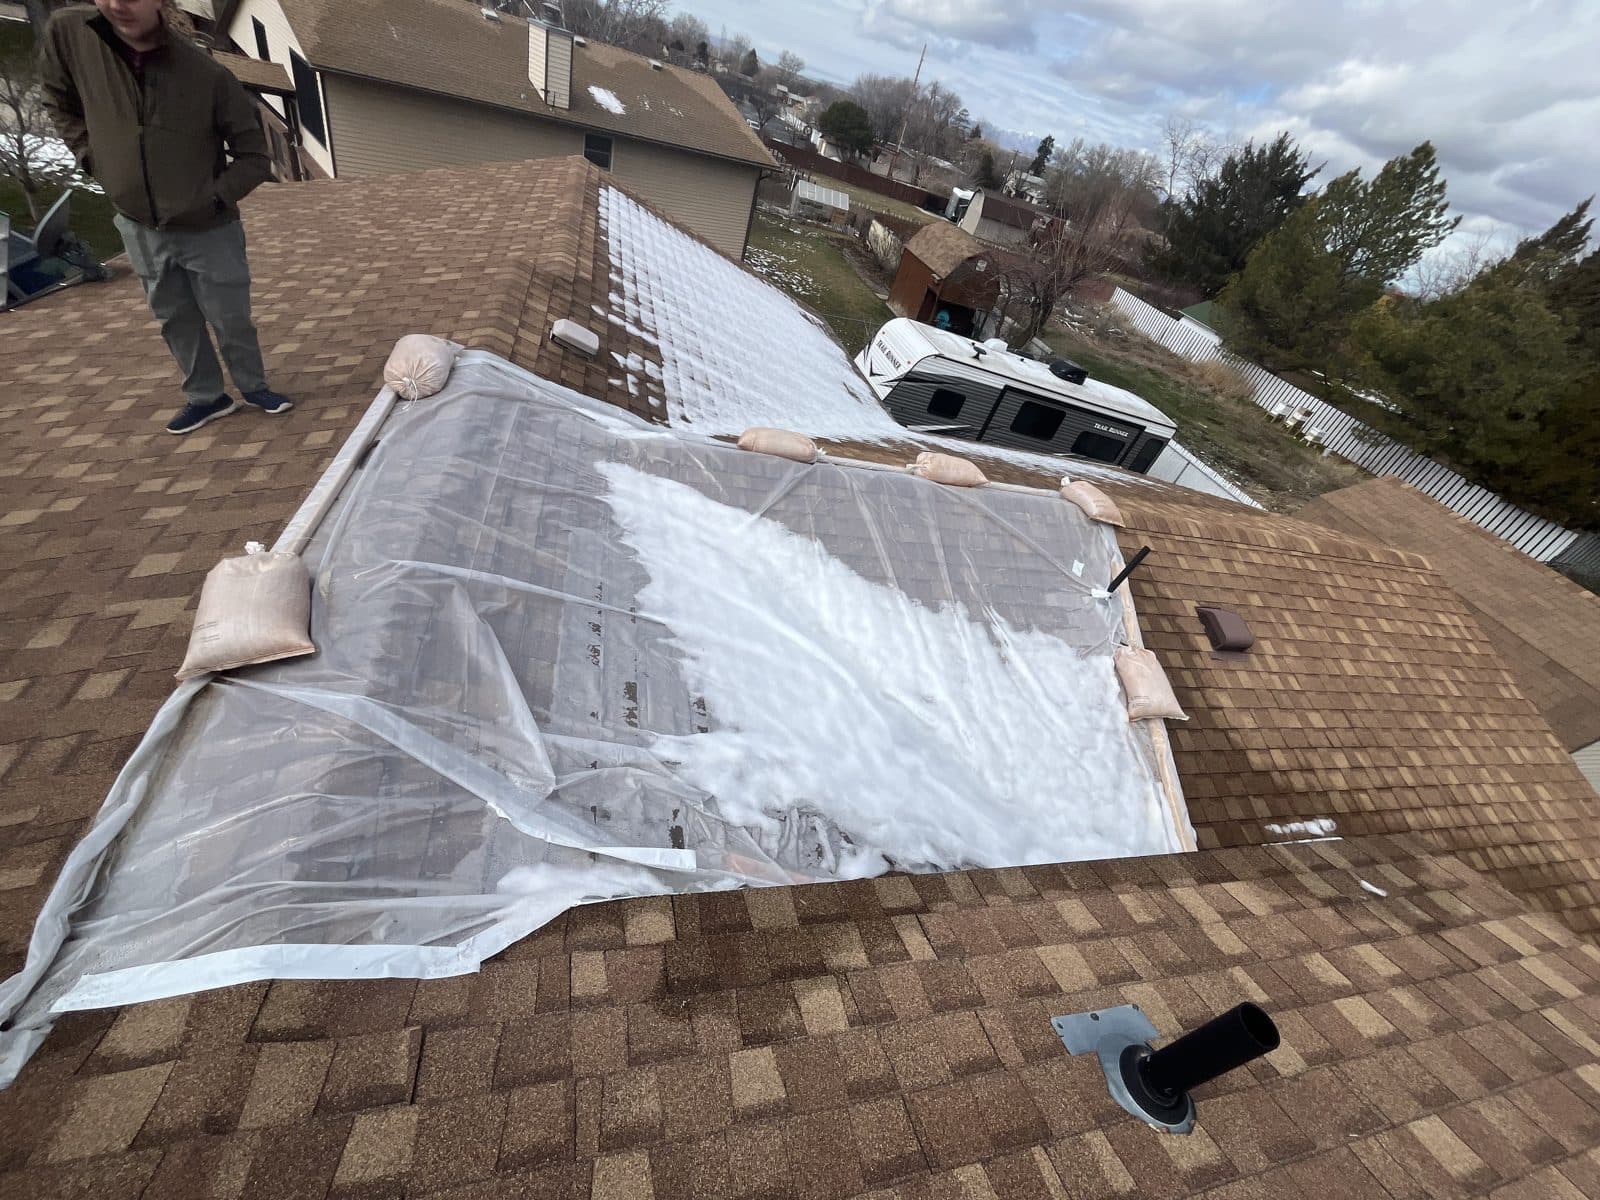
Plastic cover and sandbags on a roof section 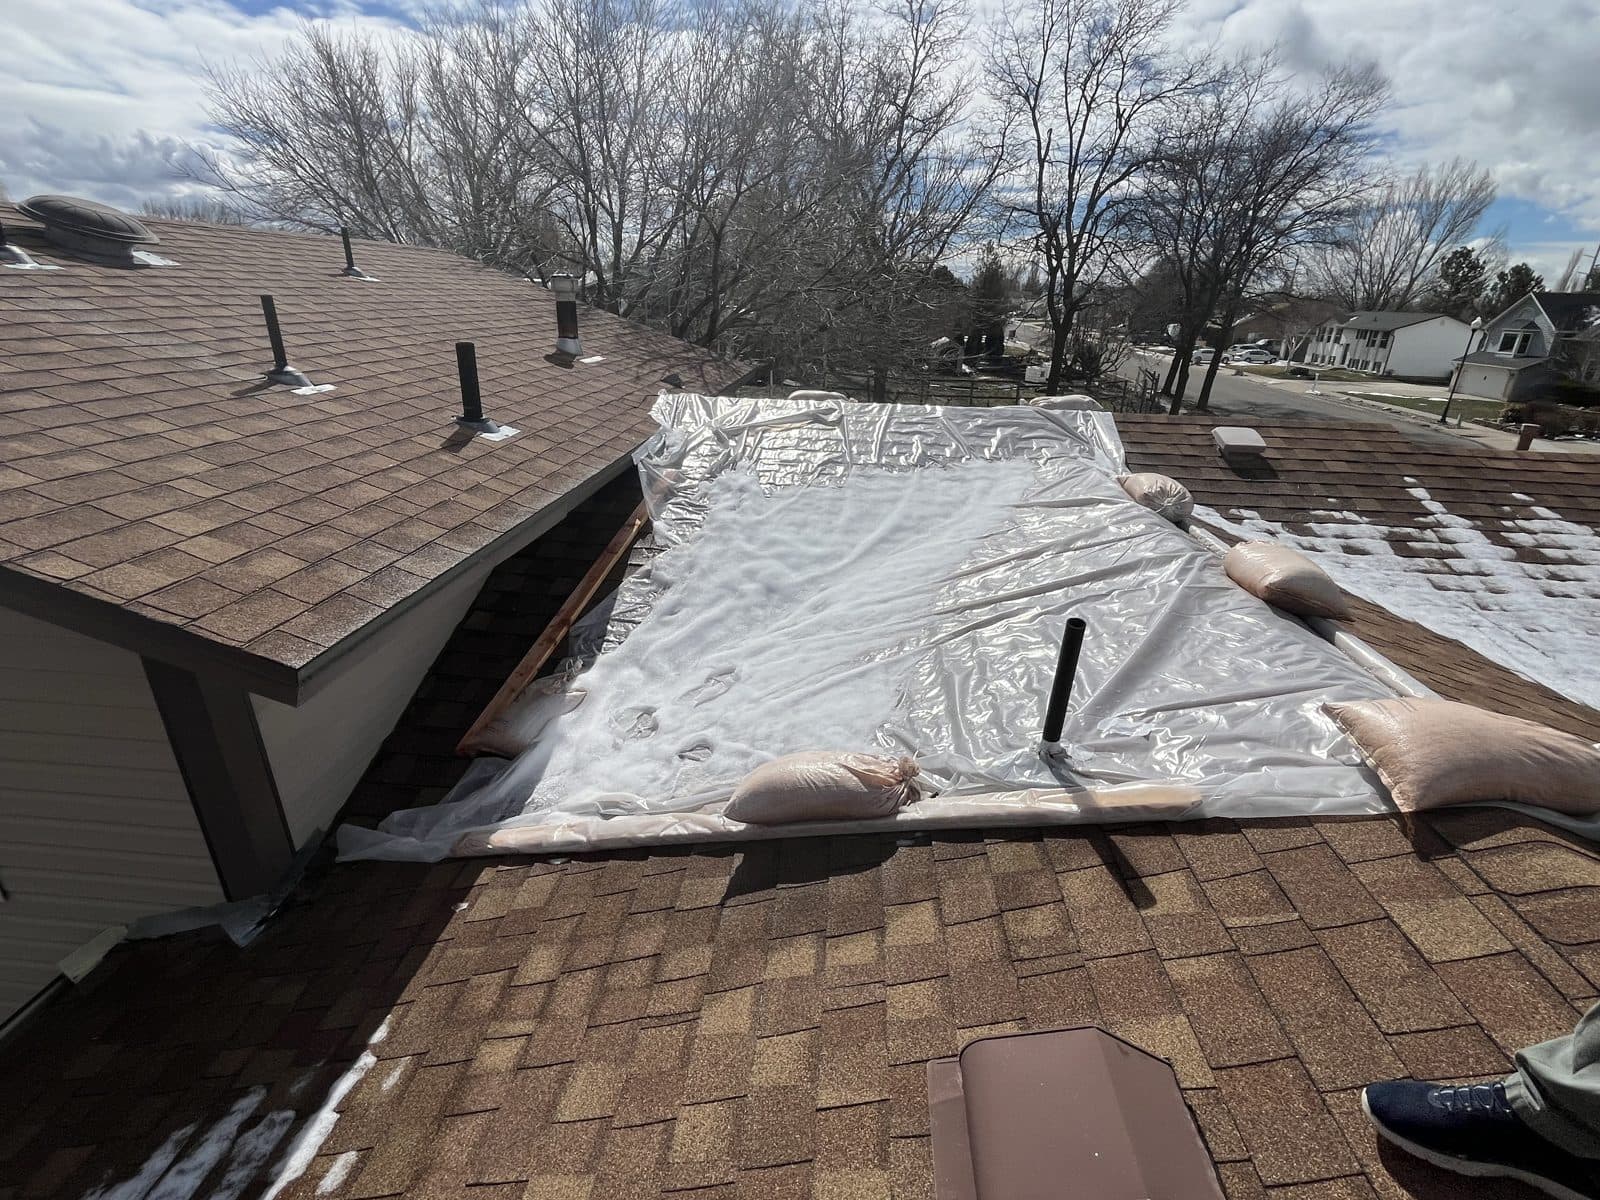
Plastic emergency cover over a roof section 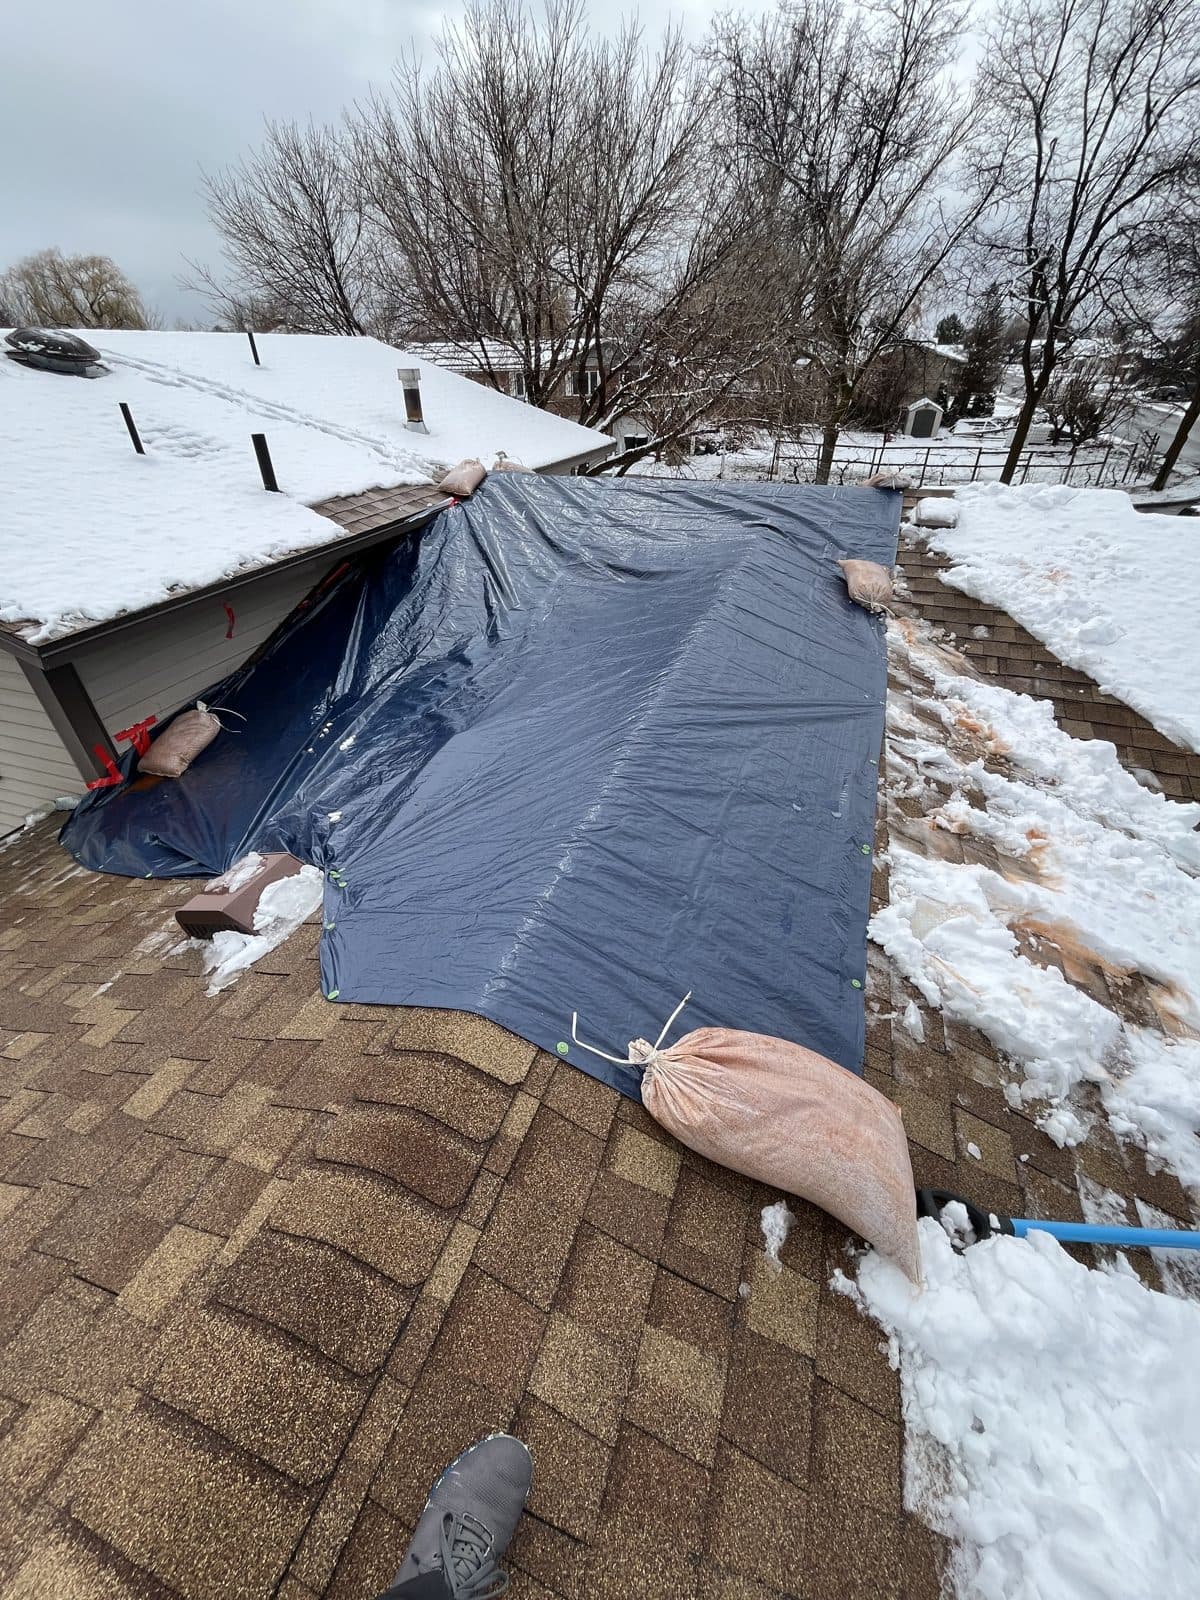
Blue tarp and sandbags in the snow 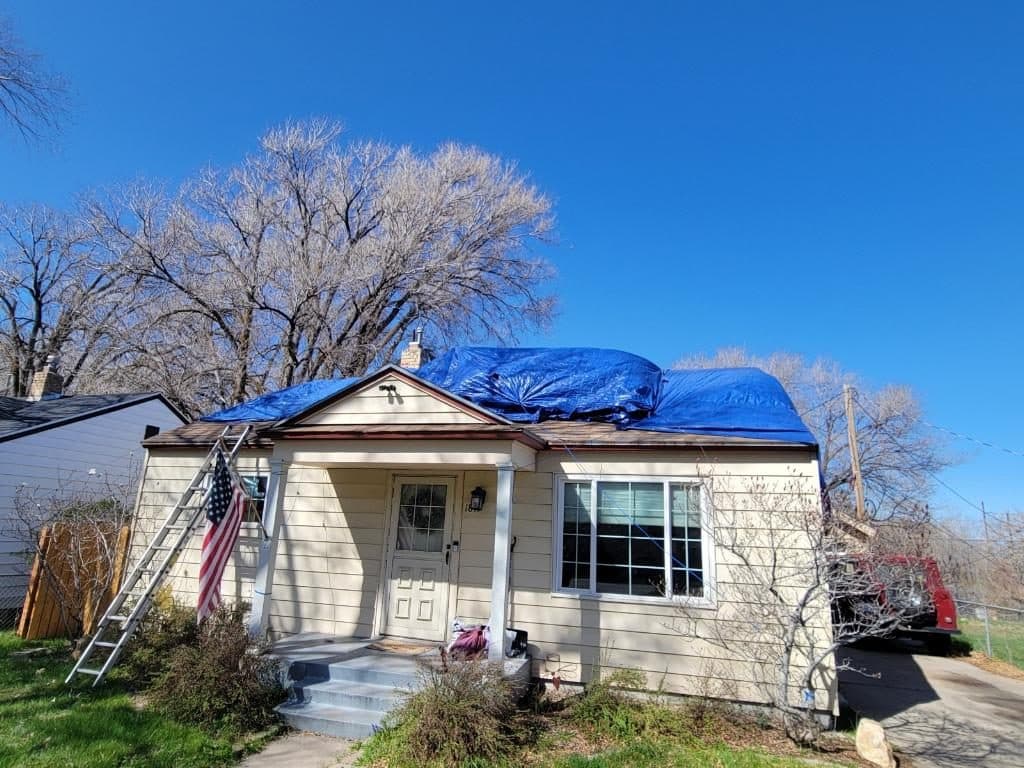
Emergency tarp over the whole roof 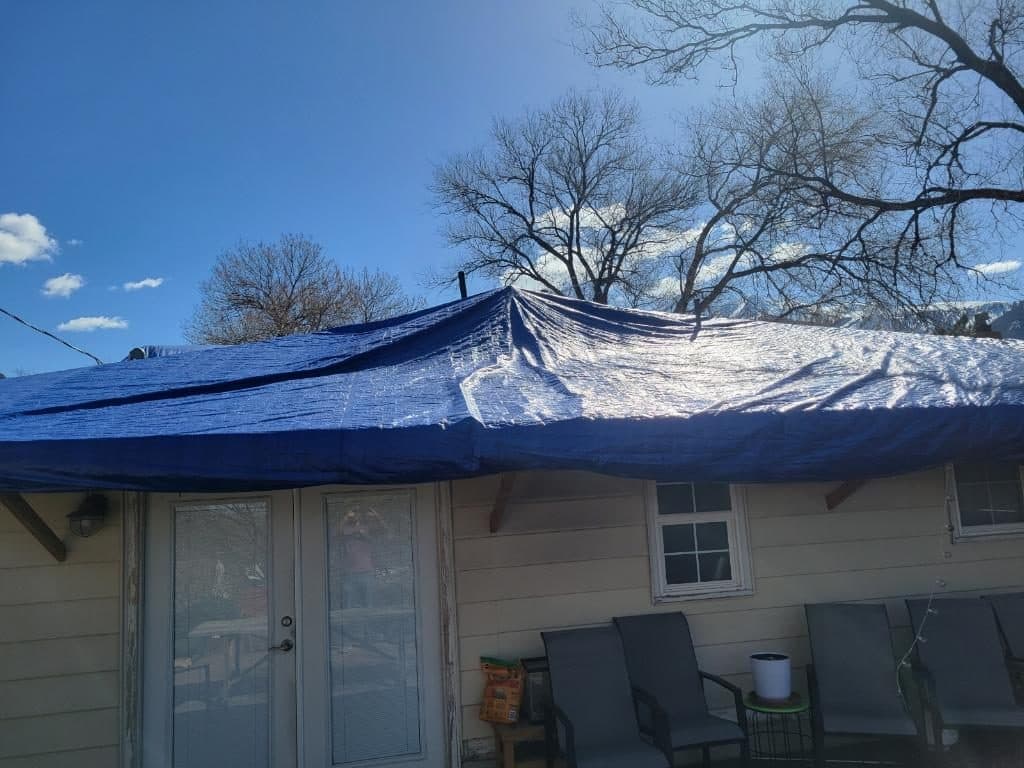
Blue tarp over a two-story roof
What hail actually does
On asphalt shingles, functional damage is bruising you can feel, fractured mats, and granule loss down to the asphalt — not a shiny spot that disappears when the roof dries. On metal, a dent is not always a leak. Paint and warranty are a different question from whether water is entering. On concrete tile, look for cracks and corner breaks, then look at the underlayment, because the tile is the armor and the membrane is the roof.
Wind is often mixed in. A storm that hails also lifts tabs, spins vent caps, and dumps debris into valleys. We separate those so an estimate does not call everything hail.
What a temporary cover does
When snow is already on the roof, or another cell is coming, an open deck or a torn section gets a plastic sheet or a blue tarp held down with sandbags. Sometimes that is one damaged area. Sometimes the cover goes over the whole house. The phone is answered 24/7 for that call: (385) 333-9637. Office hours for estimates are still 9:00 AM to 5:00 PM, seven days.
A tarp is a temporary dry-in. It is not a finished repair, and it is not an approved claim. We photograph the damage when it is safe to do so before the cover goes on, because a tarp changes what an adjuster can see. We do not promise how soon a crew will arrive.
What we do on a claim, and what we do not
We inspect, photograph, and mark a roof so an adjuster can see what we see. We will meet the adjuster when you want us there. We explain the scope we would build if the roof is replaced or repaired. You remain the insured. The carrier decides coverage. We do not tell you a claim is “basically approved,” and we do not suggest starting a tear-off that you can only afford if the check arrives.
We also do not offer to waive a deductible or to hide that number inside a bigger invoice. That pitch is common after a storm and it is a problem, not a favor. If your deductible is large, the honest math might be that a repair is yours to pay or that the roof is a maintenance item, not a claim.
- A written description of damage by slope, not a single “whole roof” sentence
- Photos before a tarp or a repair changes the evidence
- Attendance at the adjuster meeting when you ask for it
- A construction scope that can be compared with the carrier’s scope
- No guarantee of payment, coverage, or matching
Matching and code
Discontinued shingles and faded slopes make a repair obvious. Some policies address matching and some do not. That is a policy question for your agent and the adjuster, not a promise from a roofer. Building-code items — ice-and-water, drip edge, decking that no longer meets the nailing you need — belong in the construction scope as construction, and you should see which of them the carrier is treating as covered.
We will not invent code requirements to inflate a claim. We will name the ones the city actually enforces on a replacement.
After the storm, before you sign
Door-to-door crews multiply after a Wasatch hail event. Ask who pulls the permit in your city, who is on the contract, and whether they will still be here in eight weeks. A local scope you can reread is worth more than a same-day contingency form.
Cities where this comes up
These are examples, not a coverage limit. Every city page links the services that matter there.
Storm, hail, and insurance claims questions
Do you tarp roofs after hours?
Yes. Call (385) 333-9637. The phone is answered 24/7 for emergency tarping. A plastic cover or a blue tarp with sandbags is a temporary dry-in, not a repair and not a promise that insurance will pay. Office hours for estimates are 9:00 AM to 5:00 PM, seven days. We do not promise an arrival time.
Can you guarantee my insurance will pay for a new roof?
No. Coverage depends on your policy, the deductible, and what the adjuster agrees is storm damage rather than wear. We can show the damage clearly. We cannot, and will not, promise a payment.
Should I file a claim before anyone looks?
Talk with your agent about how a claim affects you, then have the roof looked at by someone who will tell you if the damage is real. Filing because a canvasser said the whole subdivision is getting free roofs is how people open claims they did not need.
Do you waive the deductible?
No. Pay the deductible that your policy requires. A contractor who offers to eat it is telling you the invoice and the scope are not the same document.
What if only one slope was hit?
Then the honest construction scope may be that slope, plus any flashing the repair disturbs. If the shingle cannot be matched, we say that. Whether the carrier owes you more than the damaged slope is their decision under the policy, not a line we add for convenience.
How fast should damage be documented?
Before the next storm and before a temporary repair covers it, if you can do both safely. Hail bruises do not need to be photographed from a ladder in the lightning. They do need to be recorded before a year of sun makes the argument harder.
Related work
- Roof repairLeaks, flashing, pipe boots, and storm-lifted shingles — repaired when a repair will last, and declined when it will not.
- Full roof replacementTear off the old roof, inspect the deck, and install a system specified for that city’s snow, wind, and sun.
- Roof inspectionsA written look at the roof for a leak, a sale, or a storm — scoped to the roof, not disguised as a whole-house inspection.
- Asphalt shingle roofingArchitectural shingles — the default Wasatch roof — detailed for UV at elevation, ice at the eaves, and local wind.
Ask about storm and hail.
The inspection is free when it is tied to work we might do. The written scope comes after we have seen the roof.
Emergency roof calls answered 24/7. (385) 333-9637.